Key takeaways
- Existing log homes can qualify for standard mortgages — the hurdle is usually the appraisal, not the logs.
- Appraisers need comparable sales; in areas with few log homes, values can come in low or the appraisal can fail.
- Large acreage, rural access, and insurance availability all affect which lenders will say yes.
- Cabins bought as short-term rentals can qualify on projected rental income through DSCR programs.
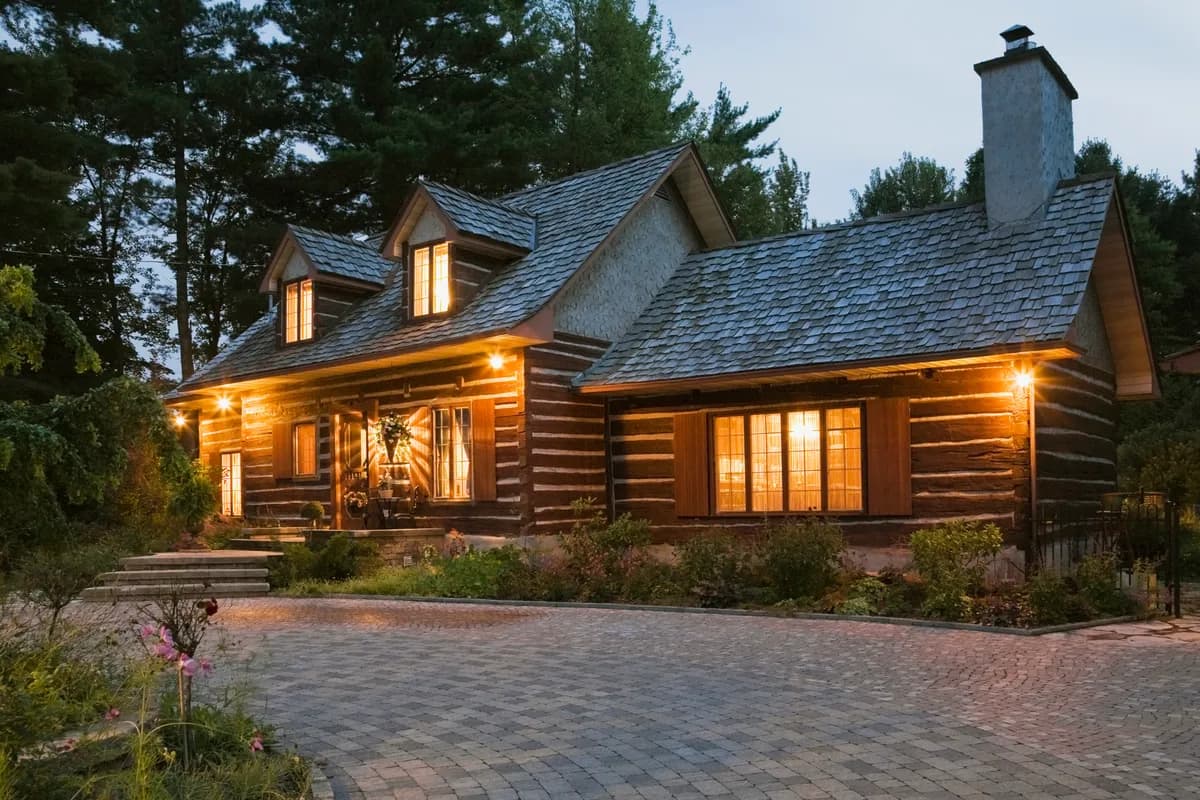
There's a persistent belief that log homes are hard to finance. Existing, well-maintained log homes in areas where they're common get ordinary mortgages every day. The difficulty depends on three things: comparable sales, the property's condition, and how rural it is. Getting those right is most of the work.
Why lenders are cautious
A lender's security is the appraised value, and the appraisal relies on comparable recent sales. In the Smokies, the Ozarks, the Rockies, or the Northwoods, there may be plenty of log homes to compare. Elsewhere, the appraiser may be forced to use conventional frame homes and make adjustments — and if no reasonable comparables exist, the appraisal can fail outright. Log construction also has maintenance issues frame homes don't: moisture, rot, insect damage, and settling as logs dry, which affects doors, windows, and chinking.
What underwriters and appraisers look for
- Comparable sales of log or similar rustic homes, ideally within the same market and the past year.
- Condition: sound logs, intact sealant and chinking, good drainage, and no active rot or insect damage. Get an inspector who knows log construction.
- Acreage: many standard programs limit how much land value can count, and large tracts can push the loan toward a land or portfolio lender.
- Access: year-round road access, sometimes with a recorded road maintenance agreement for private roads.
- Utilities: well and septic are common and acceptable, usually with water and septic inspections.
- Insurance: availability and cost, especially in wildfire areas or far from a fire station.
Loan options
- Conventional, FHA, VA, and USDA loans work for existing log homes that appraise and meet property standards. USDA can fit rural cabins in eligible areas for a primary residence.
- Second-home financing fits a cabin you'll use yourself; the rules are in second home vs. investment property and vacation home financing.
- Portfolio lenders and local credit unions, which hold the loans themselves and know local log-home values — see what is a portfolio loan.
- Construction loans for building from a log home kit, converted to a permanent mortgage after completion. See construction loans for investment property.
Financing a cabin rental
Cabins are among the strongest short-term rental properties in many markets, and that changes the financing conversation. A DSCR loan qualifies the purchase on the property's rental income instead of yours, and some lenders accept short-term rental income based on the property's booking history or a market projection. Down payments for short-term rentals are typically higher than for long-term rentals. Confirm that local zoning and any HOA allow short-term rentals before you rely on the income. The details are in financing an Airbnb, and the investment property program covers the rest. Run the numbers in the DSCR calculator.
Kit homes and new construction
Building a log home is a construction financing question first. Many lenders want an established builder, full plans, a budget, and a draw schedule tied to inspections. The land often serves as part of the down payment if you already own it. Ask early how the lender will appraise the finished home, because the comparable-sales question applies to the completed value too.
Tips that save deals
- Ask your agent for recent log-home sales before you offer, and share them with the lender.
- Order a specialist inspection — log homes need someone who knows how to check moisture and decay.
- Get insurance quotes during the inspection period, not after.
- If the appraisal comes back low, an appraisal gap strategy may keep the deal together.
- Unique property types like barndominiums face many of the same comparable-sales questions.
Found a cabin you love? Send me the listing and how you plan to use it — full-time home, getaway, or rental — and I'll tell you which loan fits and what the appraiser is likely to need. Property eligibility varies by lender and program.
Have a situation like this?
Every file is different. Book a free consultation and get answers specific to you — no obligation, no pressure.
Book a Free Consultation